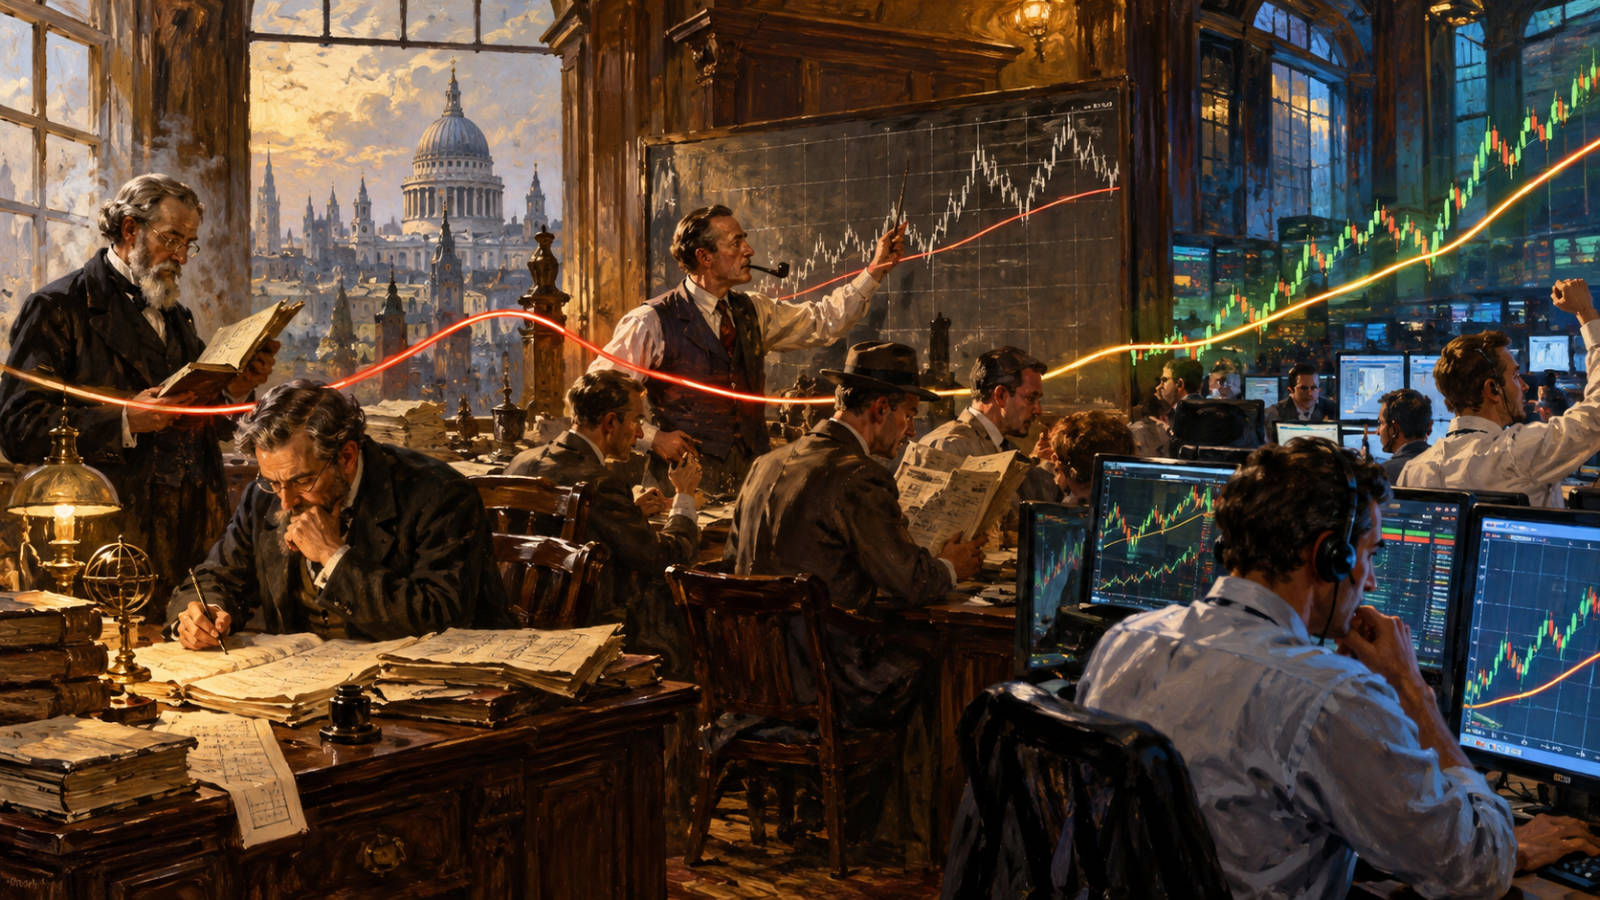
Image by: Knelstrom Media.
MOVING AVERAGE: The quiet line that taught markets to follow themselves
By Martin Foskett, Reporter
PUBLISHED:
UPDATED:
The moving average may be the least glamorous object ever to gain near-mystical status in financial markets. It is a line calculated from old prices, dragged across a chart like a length of electrical cable, and consulted daily by traders controlling sums large enough to purchase respectable portions of Essex. Yet behind that modest line sits more than a century of statistical thinking, market experimentation and the stubborn human desire to work out whether prices are actually going somewhere.
Its ancestry belongs to statistics rather than Wall Street.
In the late nineteenth and early twentieth centuries, statisticians developed methods for smoothing unruly sequences of numbers. Economic data, crop prices, industrial production and other time series had an irritating habit of jumping about. Averaging observations helped reveal the underlying direction beneath the racket.
That principle was beautifully simple. Take a collection of recent observations, calculate their average, move forward one period and calculate it again. The resulting sequence suppresses some short-term noise.
Markets eventually recognised the idea’s usefulness.
Charles Dow had already established an intellectual foundation for studying market trends around the turn of the twentieth century. Dow Theory was not itself a moving average system, but its central proposition mattered enormously. Markets developed identifiable primary and secondary trends. Price action therefore contained information worth studying rather than being dismissed as the financial equivalent of pigeons scattering across Trafalgar Square.
Technical analysis grew from that soil.
By the 1930s, Richard Donchian was pushing matters towards something recognisably modern. Donchian, later celebrated as one of the fathers of trend following, developed systematic trading ideas involving different moving averages. His work eventually became closely associated with five- and twenty-day averages.
The importance lay in more than the lines themselves.
A trader no longer needed a mysterious feeling in the stomach, a racehorse owner’s telephone number or an acquaintance standing near the exchange. A rule could determine when conditions had changed.
That was revolutionary.
By the postwar decades, moving averages were becoming fixtures of technical market analysis. The 200-day moving average emerged as a particularly popular gauge of the long-term trend, while shorter measures such as the 20- and 50-day averages became common tools for assessing intermediate movement.
Then computers arrived and removed the arithmetic.
What had once required pencils, graph paper and patience could suddenly be calculated continuously. Electronic charting eventually turned moving averages into standard equipment. Modern trading platforms now allow practically anyone with an internet connection and an alarming level of confidence to cover a chart with enough coloured averages to resemble the wiring diagram from a 1978 Ford Capri.
Fortunately, the mathematics remains less frightening.
A simple moving average, or SMA, takes the closing prices from a chosen number of periods, adds them together and divides the result by the number of periods.
A 20-day SMA therefore represents the average closing price over the previous twenty trading sessions. Tomorrow the oldest observation disappears, and the newest enters; the average moves.
An exponential moving average, or EMA, changes the weighting. Recent prices carry more weight, making the line react faster to changing market conditions.
Neither version predicts the future.
That distinction is where many trading accounts have met an undignified end.
Moving averages are lagging indicators. They describe what prices have already done in a form designed to make the underlying trend easier to recognise. They cannot announce next Thursday’s market direction like a railway departure board.
Their practical value comes from the structure they impose.
Suppose a trader places a 200-day SMA on a daily chart. Price consistently above a rising 200-day average suggests an established long-term uptrend. Price consistently below a falling average suggests the opposite.
The line’s direction matters as much as price’s position.
A market sitting fractionally above a sharply falling average is hardly displaying magnificent health. Context remains king, however desperately charting software tries to crown the indicator instead.
Two averages can also be combined.
A trader might use a 50-day average alongside a 200-day average. When the shorter average rises above the longer one, technicians commonly call it a golden cross. When it falls below, the rather more theatrical expression is death cross.
The names sound as though medieval cavalry should appear shortly afterwards. In reality, both merely confirm that shorter-term price behaviour has changed relative to the longer-term trend.
Shorter-term traders can apply the same principle using faster combinations such as 10 and 20 periods, or 20 and 50. The appropriate setting depends upon the market, timeframe, trading costs and strategy. No sacred number comes from the mountain.
Moving averages can also act as dynamic reference areas.
During a strong trend, price may repeatedly retreat towards a rising average before continuing higher. Traders sometimes use those pullbacks to identify potential entries, provided other evidence supports the trade.
That last condition matters.
A moving average should not become an automated permission slip for throwing capital at a screen.
Volume, market structure, support and resistance, volatility and risk management can all provide useful context. More importantly, every trade requires an exit plan. Determine position size before enthusiasm starts doing the arithmetic.
The great weakness appears when markets stop trending.
Sideways markets are moving average slaughterhouses.
Price crosses above the average. A buy signal appears. Price falls back. The trader exits. Another signal arrives. Then another. Commissions, spreads, slippage, and small losses begin removing money with the quiet efficiency of a council parking department.
This phenomenon is known as whipsaw, and Donchian understood the problem decades ago.
Trend following accepts those irritating losses because the strategy is designed to capture occasional sustained moves. The trader sacrifices the impossible ambition of buying the exact bottom and selling the exact top. Instead, confirmation is purchased at the cost of entering late and leaving late.
That trade-off remains the heart of the moving average.
A sensible modern approach is therefore surprisingly plain. Identify the intended timeframe. Choose an average appropriate to it. Define what constitutes a trend. Establish the precise entry condition. Decide where the trade is wrong. Determine position size from that risk. Test the rules across different market conditions before risking meaningful capital.
Then leave the settings alone long enough to discover whether they actually work.
Constantly changing a 50-day average to 47 because the historical chart suddenly looks prettier is not research. It is fitting yesterday’s suit to tomorrow’s customer.
More than a century after statisticians began smoothing awkward sets of numbers, the moving average survives because markets still contain exactly what it was designed to expose: direction hidden inside noise.
The indicator is not clever. That may be its greatest virtue.
Governments produce forecasts hundreds of pages long. Banks employ armies of economists. Financial television can turn a quarter-point interest rate decision into something resembling the moon landing. Meanwhile, the moving average takes the prices, smooths them and waits.
It promises nothing.
Used properly, it tells a trader what the market has been doing and helps establish rules for what happens next. Used badly, it becomes another colourful line onto which hope is projected.
The arithmetic has never been the difficult part.
The difficult part has always been persuading the human being holding the mouse to obey it.
[adinserter name=”Block 1″]